20% more orders. 8% more revenue. 10% less left for the bills. Why a sale can look better than it is.
The shop below is a worked example, not a real company or a reported experiment. All amounts exclude VAT.
The sale looks like a success. Orders are up. Revenue is up. There are more parcels to pack.
Then you add up what is left after fulfilling those orders. It is less than you would have kept without the sale.
Nothing went missing. The discount worked exactly as advertised: customers paid less. The extra orders just did not make up the difference.
Imagine a small homeware shop selling a €50 product. Buying it, packing it, delivering it and taking payment cost €30 per order in our example. That leaves €20 to cover the shop’s fixed bills and, eventually, profit.
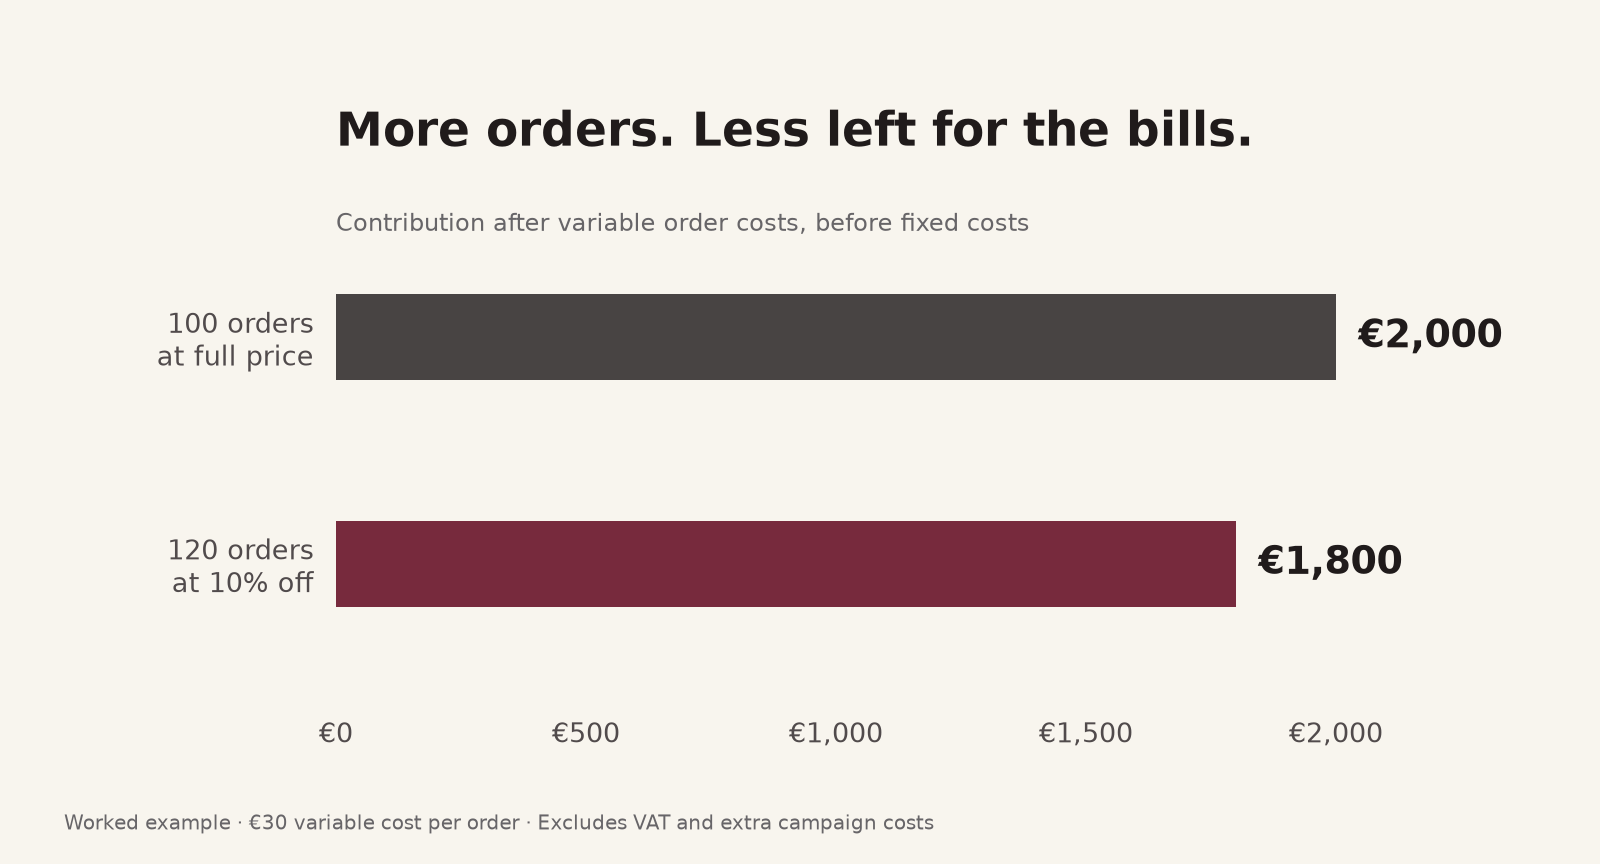
Without a promotion, suppose the shop would sell 100 orders. It would have €2,000 left after those order costs.
The owner offers 10% off. The price drops to €45, and orders increase to 120.
Here is the result:
| Without the sale | With 10% off | |
|---|---|---|
| Orders | 100 | 120 |
| Price per order | €50 | €45 |
| Revenue | €5,000 | €5,400 |
| Total order costs | €3,000 | €3,600 |
| Left for fixed bills and profit | €2,000 | €1,800 |
Revenue rose 8%. The money left fell 10%.
Accountants call that remaining money contribution. It is not net profit: rent, software and other fixed expenses still have to come out of it. But if those bills stay the same, having €200 less available makes the business €200 worse off.
A 10% discount takes 25% of what you kept
The surprising part is how much a small discount takes from that €20.
The customer saves €5. The shop gives up €5 of the €20 it previously kept. A 10% price reduction removes 25% of the contribution per order.
There is another way to see the problem. Our example assumes 100 orders would have happened at full price. Giving those orders €5 off costs €500. The 20 additional orders contribute €15 each, bringing back only €300.
Under those assumptions, the promotion gives away €500 to generate €300. That is the missing €200.
The target is 134 orders, not 120
To preserve the original €2,000, the shop needs €2,000 divided by €15: 133.3 orders. In practice, at least 134 orders.
So this particular 10% discount needs 34% more whole orders just to match or slightly exceed the previous contribution. Getting 20% more feels impressive, but it falls short.
The deeper the discount, the harder the recovery becomes:
| Discount | Left per order | Orders needed to retain at least €2,000 |
|---|---|---|
| None | €20 | 100 |
| 5% | €17.50 | 115 |
| 10% | €15 | 134 |
| 15% | €12.50 | 160 |
| 20% | €10 | 200 |
These numbers depend on this shop’s costs. A business keeping €35 from a €50 order has more room to discount than one keeping €10. Copying another shop’s sale percentage tells you very little about whether yours can afford it.
A discount can still make sense
There can still be a good reason to run the offer. Perhaps the stock is seasonal and will soon be harder to sell. Perhaps the extra customers later return at full price. Perhaps a targeted discount reaches people who otherwise would not buy, while existing demand stays at full price.
Those are different business cases. Each needs its own evidence. In our example, future purchases would need to contribute more than the €200 shortfall, plus any additional campaign costs, before they make the decision worthwhile. Future revenue alone does not settle the bill.
Put an order target beside the offer
Before launching a sale, write down three things: what a normal order leaves, what a discounted order leaves, and how many additional orders are needed to close the gap.
For this simplified model, the calculation is:
Required orders = (contribution without the sale + extra campaign costs) ÷ contribution per discounted order.
Round up to the next whole order. Here, that is €2,000 ÷ €15 = 133.3, rounded up to 134. This target preserves the contribution you expected without the sale; it is not the shop’s overall break-even point. If a discounted order leaves nothing or loses money, selling more of those orders cannot recover the original contribution under this model.
Then include the costs of making the promotion happen. An extra €100 of advertising pushes this example’s requirement to 140 orders. Extra packing labour, different product choices and returns can change it again.
Afterward, compare the result with a credible estimate of what would have sold without the promotion. A busier shopping season can increase orders on its own; a sale can also bring forward purchases that would have happened next week. Comparing two revenue totals will not tell you which occurred.
Before the next sale, put the required order count beside the offer. For this shop, the decision reads:
10% off. We need at least 134 orders.
Sources and method
This is an original worked example, not a report about a real merchant. The order uplift is assumed, not a forecast of how customers respond to discounts. Each order contains one product; we hold variable cost per order constant to isolate the effect of the price change.
For the accounting definition and the limits of this type of analysis, see ACCA’s explanation of cost-volume-profit analysis, checked 25 October 2026. Contribution means sales less variable costs; fixed costs still need to be covered. The promotion scenarios and chart here are Webshop Toolkit’s own calculations.
Get our weekly ecommerce briefing. Sign up for the weekly email.